ATTEnTION: Self-employed home owners
Breathe Again - Get Your ATO Debt Sorted
Exclusive to property owners with profitable businesses: Turn heavy ATO tax obligations into one lower payment—we negotiate directly with lenders to protect your cash flow.
CLICK BELOW TO WATCH FIRST!

Next Step: Answer a few questions to check you meet our eligibility
If you're self employed, have a trading business and property equity, refinancing may allow you to clear ATO tax debt and move into one manageable mortgage repayment.
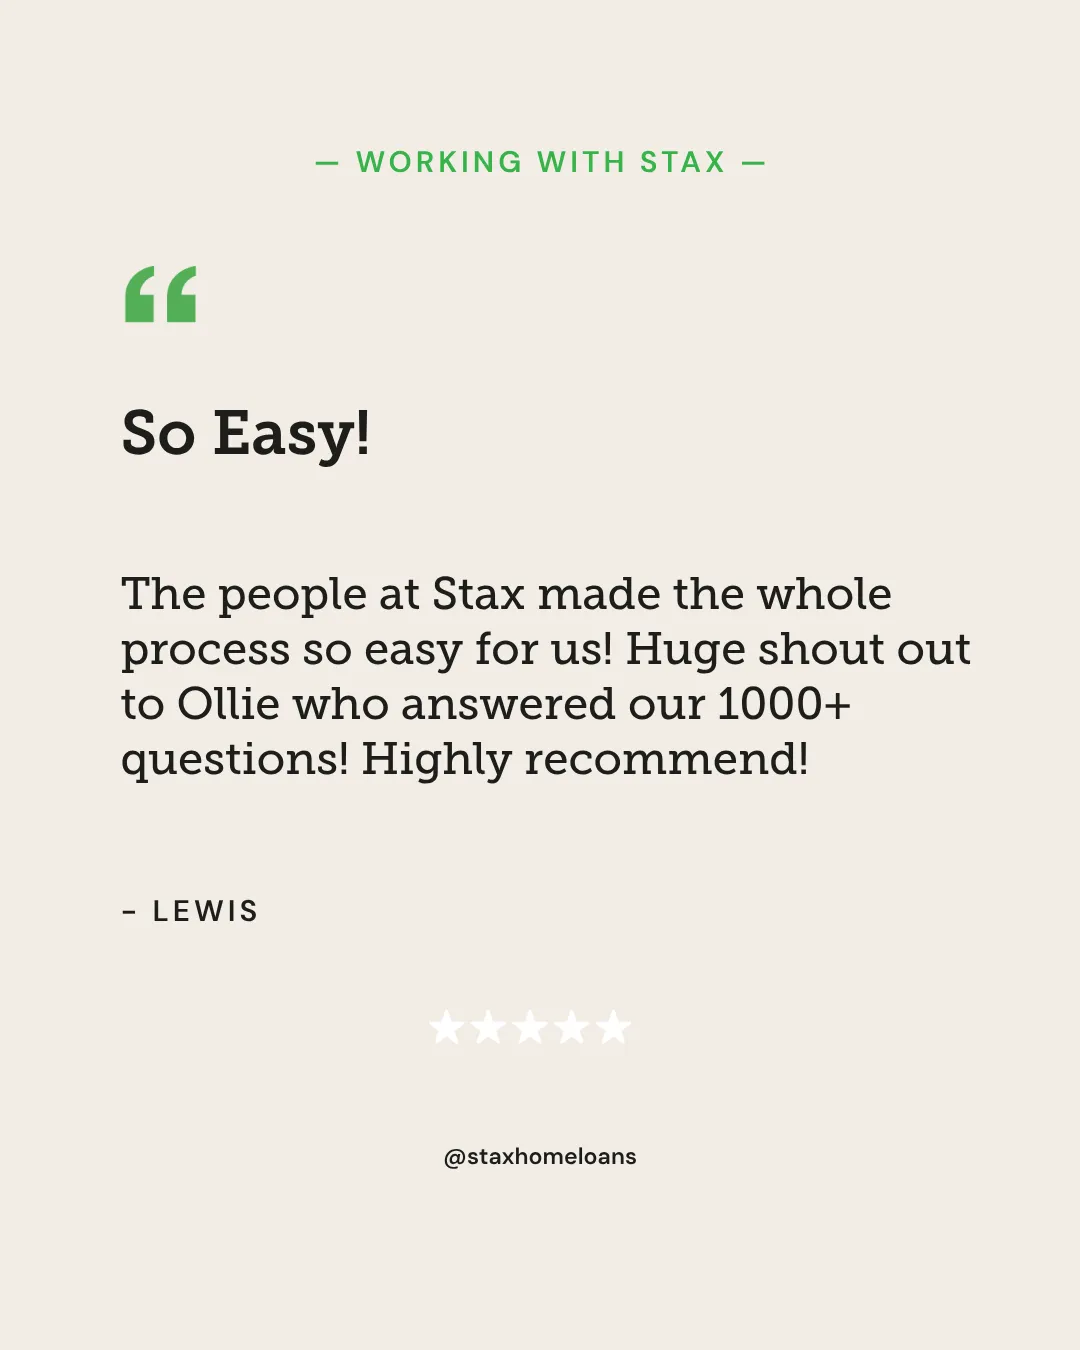
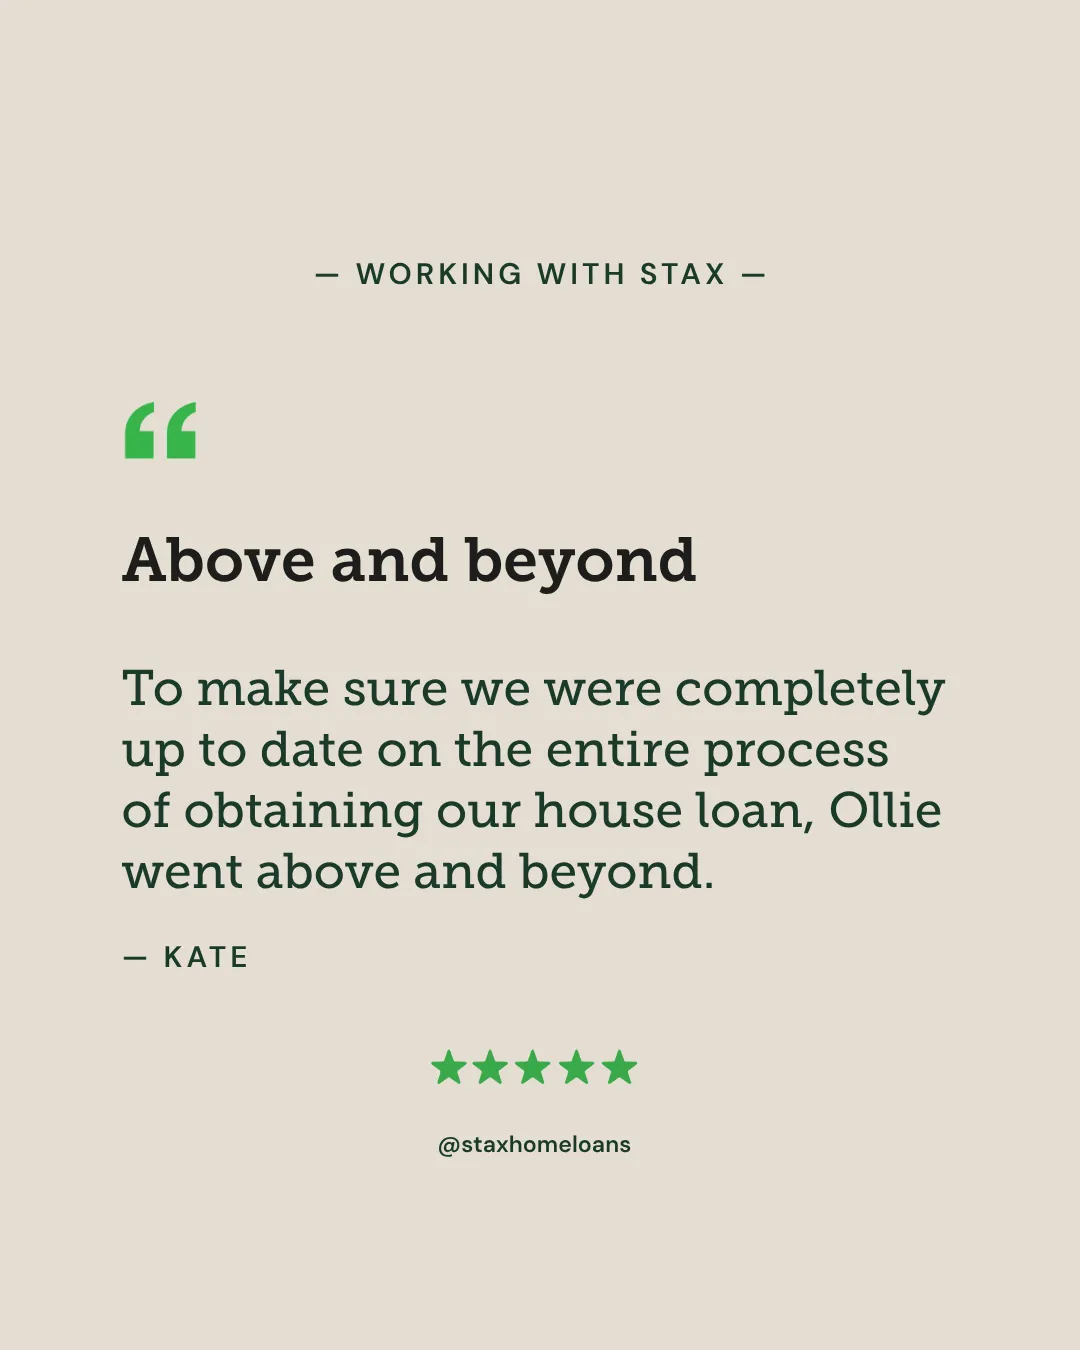
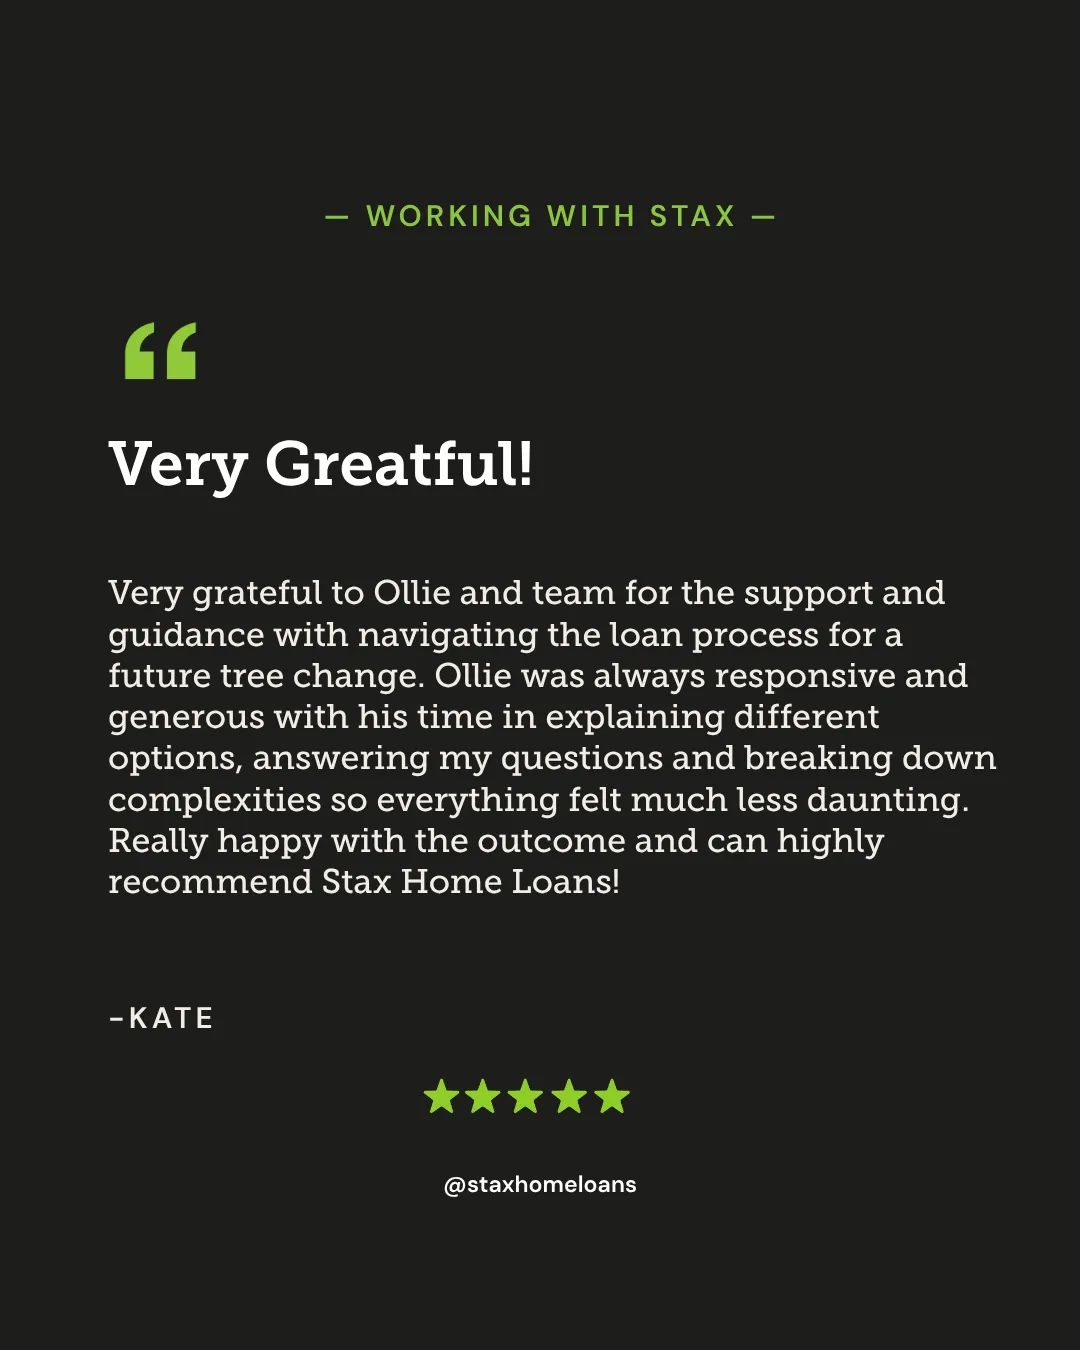
TESTIMONIALS
What others are saying
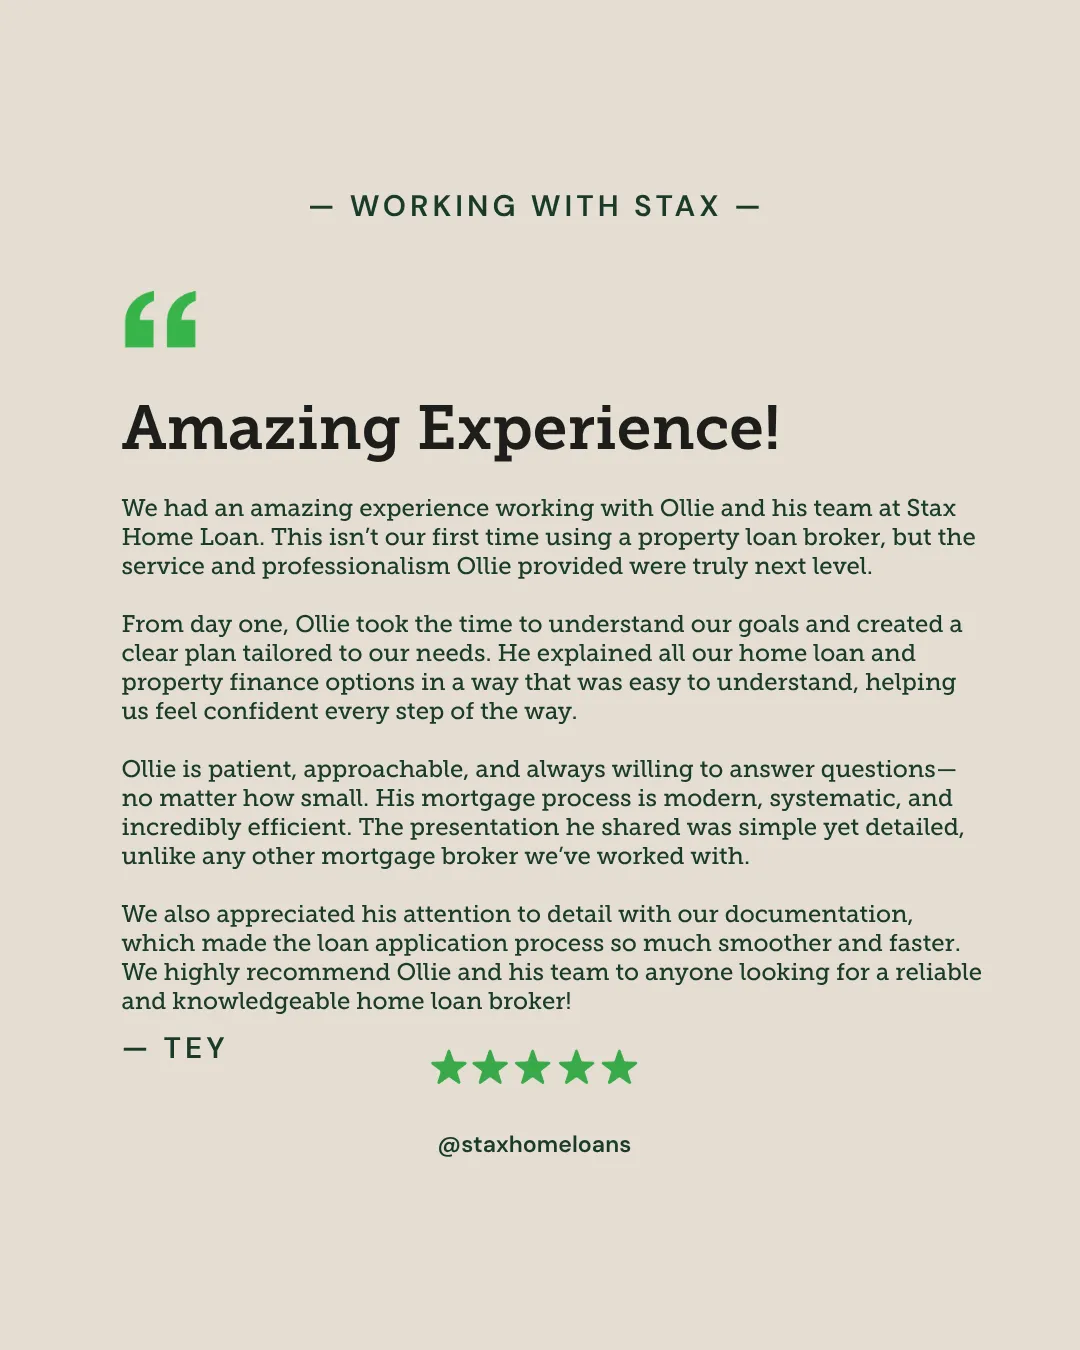
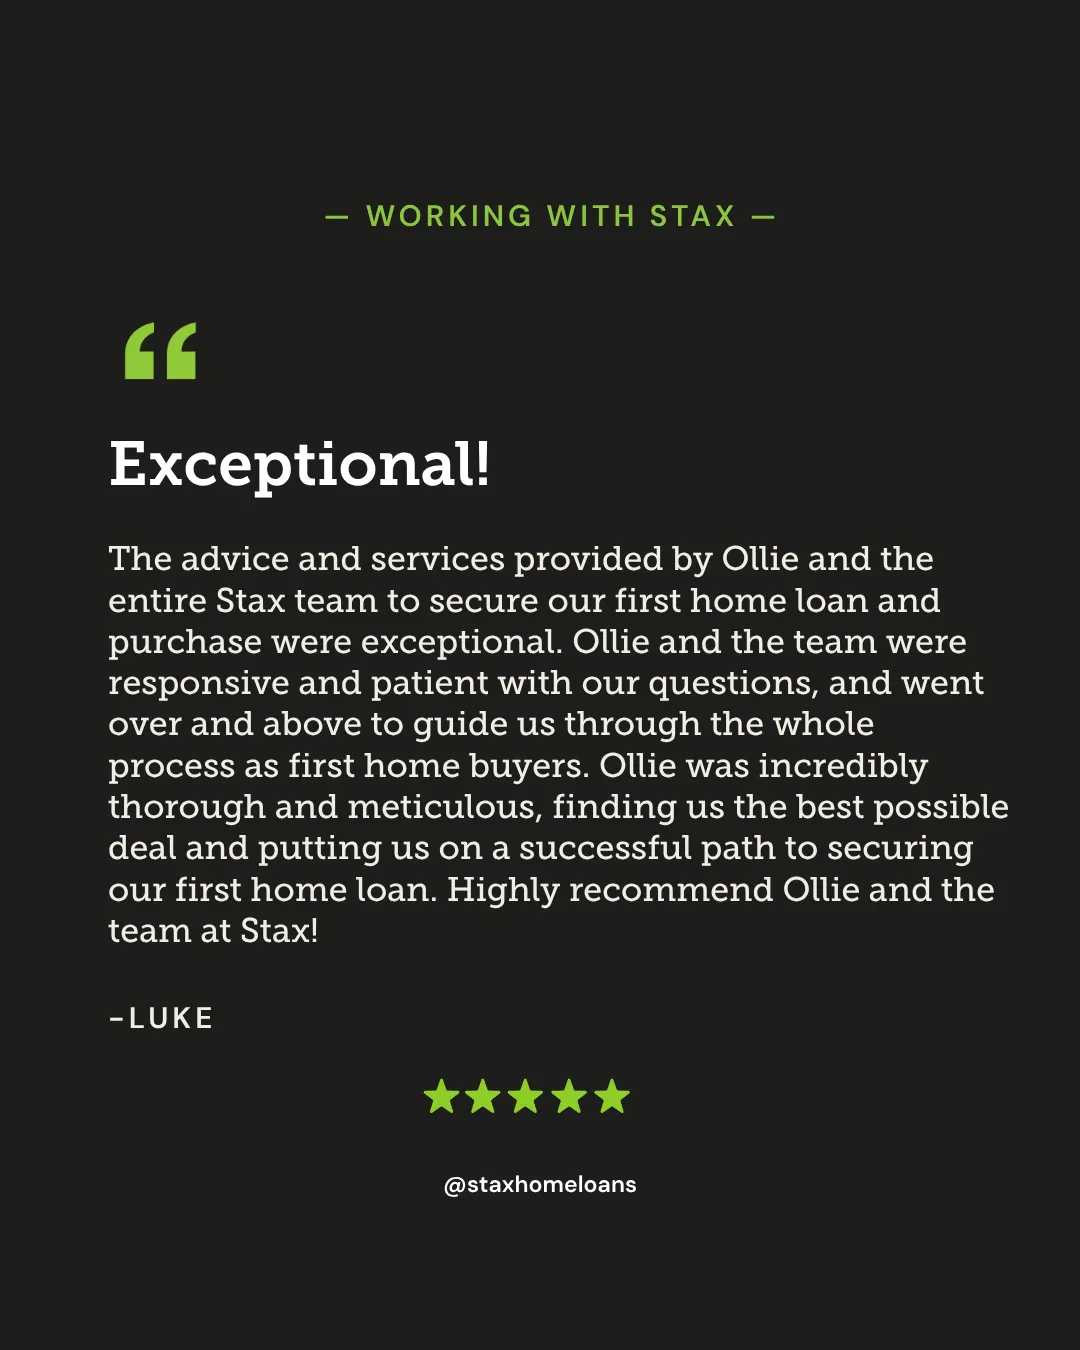
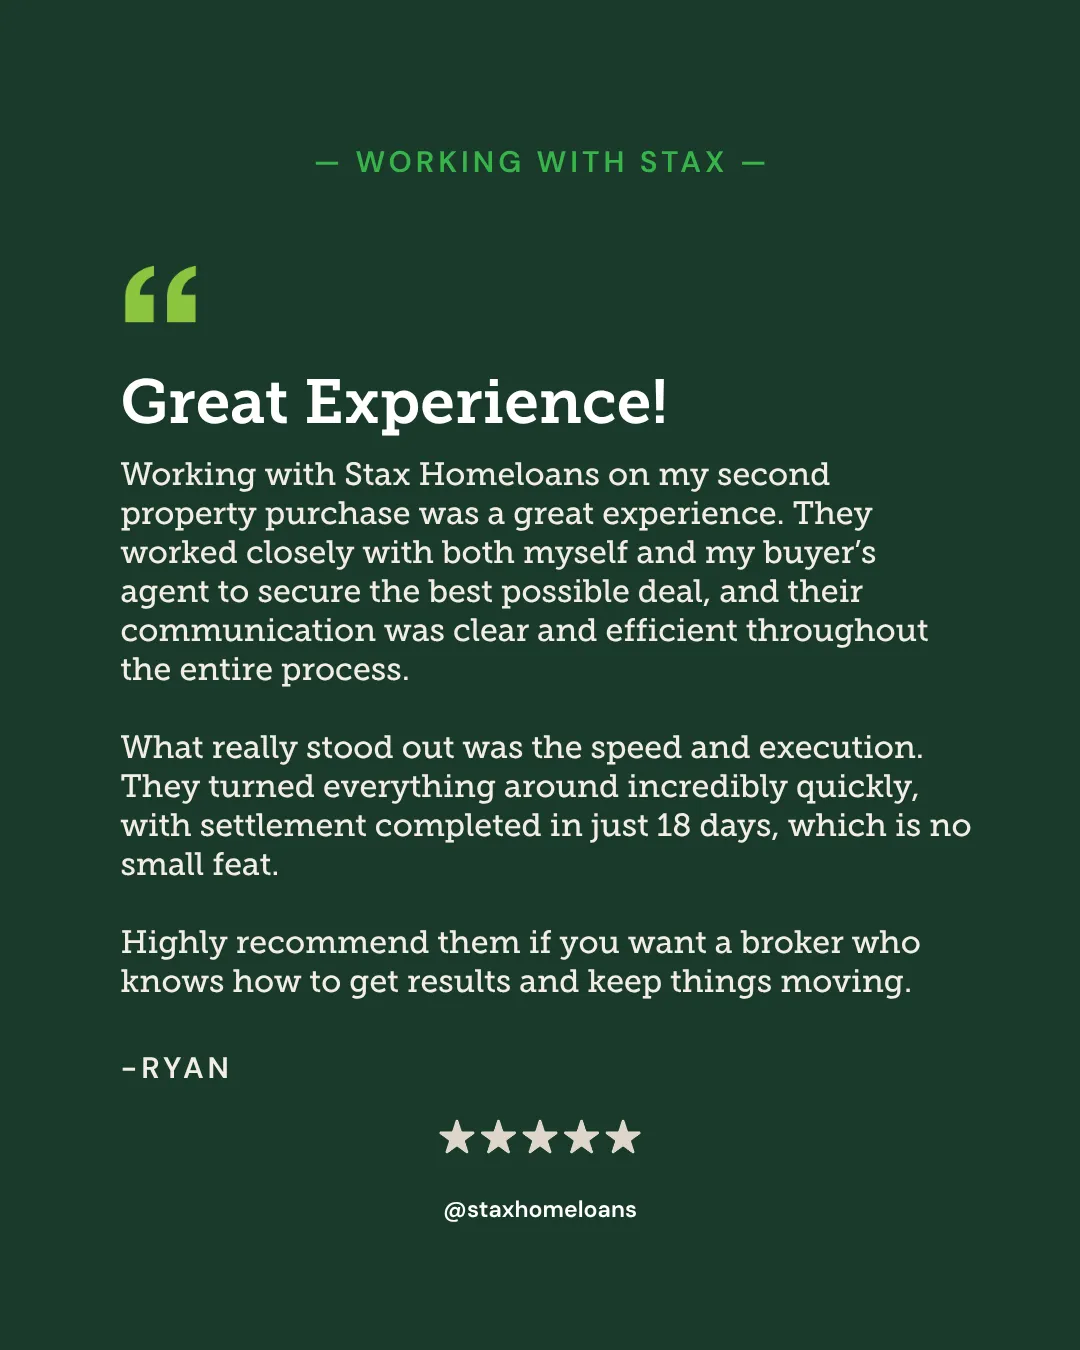
For Self Employed Home Owners That Want to Clear ATO Tax Debt
We have a track record of helping self employed clients tidy up tax debt and move on with running their businesses. We help people that ....
ARE YOU Self Employed and run a PROFITABLE business
Own a home or investment property
HAVE EQUITY IN THAT PROPERTY
HAVE ATO DEBT OR A PAYMENT PLAN
ARE PAYING ATO GENERAL INTEREST CHARGES
HAVE ONGOING INCOME FROM THE BUSINESS
STILL NOT SURE?
Frequently Asked Questions
Here's what we usually get asked
Can I really refinance my home loan if I owe money to the ATO?
Yes. While major retail banks frequently decline applications involving tax liabilities, specialist lenders allow self-employed homeowners to consolidate ATO debt directly into their mortgage, provided there is sufficient equity in the property.
Don't lenders automatically reject self-employed borrowers with tax debt?
Traditional banks often do, but specialized non-bank lenders actively cater to business owners in this exact position. They feature dedicated self-employed policies built to clear tax debts and stabilize business cash flow.
What paperwork do I need if my tax returns aren't up to date?
You do not always need fully lodged tax returns. Depending on your setup, specialist refinancing options allow for "alt-doc" (alternative documentation) income verification using recent BAS statements, business bank statements, or a letter from your accountant.
How does consolidating ATO debt into a mortgage actually help?
ATO payment plans carry strict short-term schedules and high General Interest Charges (GIC). Rolling that liability into a home loan spreads the debt over a longer term at a lower interest rate, significantly cutting your immediate monthly cash outgoings.
Will assessing my options ruin my credit score or alert the ATO?
No. An initial assessment with a broker is completely confidential and requires no hard credit checks or communication with the tax office. Your details remain fully private.
How much home equity do I need to pull this off?
Ideally, your total combined debt—your existing mortgage plus the ATO debt and any credit cards or loans—should remain under 80% of your home's current market valuation to avoid excessive fees.
Why haven't I heard of your brokerage before, and are you qualified?
Stax Home Loans are licensed Australian Mortgage Brokers (Australian Credit Licence 389898) specialising in complex self-employed finance and debt restructuring as well as standard retail home loans.
What does this cost me upfront?
The initial scenario assessment and feasibility review are completely free with zero obligation. If a specialist broker fee applies to your scenario, it is disclosed transparently before any application is submitted.
How long does the entire refinancing process take?
From your initial phone call to final settlement, the process typically takes 3 to 4 weeks depending how long it takes to get your documents together. If the ATO is pressing for urgent payment or threatening legal action, we can often request urgent valuations and expedited underwriting to secure a formal approval letter, which usually buys immediate breathing room with the tax office.
How does the ATO actually get paid—do I handle the payout myself?
No, you won't need to manage the money transfer. On settlement day, your new lender pays off your existing mortgage directly and sends the remaining cash portion straight to the ATO via BPAY using your Payment Slip Reference Number. You receive official confirmation once your ATO portal balance hits zero.
What are the exact steps from filling out this form to clearing my debt?
Step 1 (Discovery): A short phone call to review your property value, current mortgage balance, and ATO debt figure.
Step 2 (Info & Document Collection): You provide your info & documents required for us to complete no obligation free assessment—think ID's, statements, tax returns, recent BAS statements, an accountant’s letter—so we can verify your income and options.
Step 3 (Strategy & Options): We calculate your exact borrowing capacity, match you with a specialist lender, and present your projected repayments, fees, and rates.
Step 4 (Valuation & Approval): We order a property valuation and submit the application for formal lender approval.
Step 5 (Settlement & Relief): The new lender pays off your existing mortgage and the ATO directly via BPAY, consolidating everything into a single lower monthly repayment.
Will my interest rate be significantly higher with a specialist lender?
Specialist rates are slightly higher than prime retail bank rates, but they are dramatically lower than the ATO’s General Interest Charge (GIC), high-interest credit cards, or short-term business loans. Most business owners find that the massive reduction in required monthly outgoings far outweighs the slight interest variance.
I already have an ATO payment plan. Why should I refinance instead?
ATO payment plans force heavy, short-term monthly repayments—often over 12 to 24 months—which severely chokes your operating cash flow. Refinancing spreads that liability over a longer loan term, drastically reducing your monthly overhead so you can reinvest in running your business.
What if the ATO is already threatening legal action or a Director Penalty Notice (DPN)?
It is usually not too late, provided you act quickly. Specialist lenders offer expedited underwriting for urgent cases, and presenting the ATO with a formal loan approval letter shows active proof of resolution, which frequently pauses enforcement action while settlement takes place.
What if the tax debt belongs to my company (Pty Ltd) rather than me personally?
This is extremely common. You can use the equity in your residential property to clear corporate tax liabilities by structuring the payout as a director's loan or clearing intercompany accounts—a standard setup that specialist lenders and accountants handle routinely.
Am I stuck with a specialist lender forever?
No. A specialist lender is often used as a 12-to-24-month bridge. Once your tax debt is cleared, your ATO portal shows a clean zero balance, and you have a solid track record of on-time mortgage repayments, we can refinance you back to a standard major bank at prime market rates.
How We Get Relief from ATO Tax Debt Repayments
Step 1
Review your scenario & collect some documents
Step 2
Prepare a "Game Plan" including lender recommendation
Step 3
Refinance & Reset
Ready to get started?
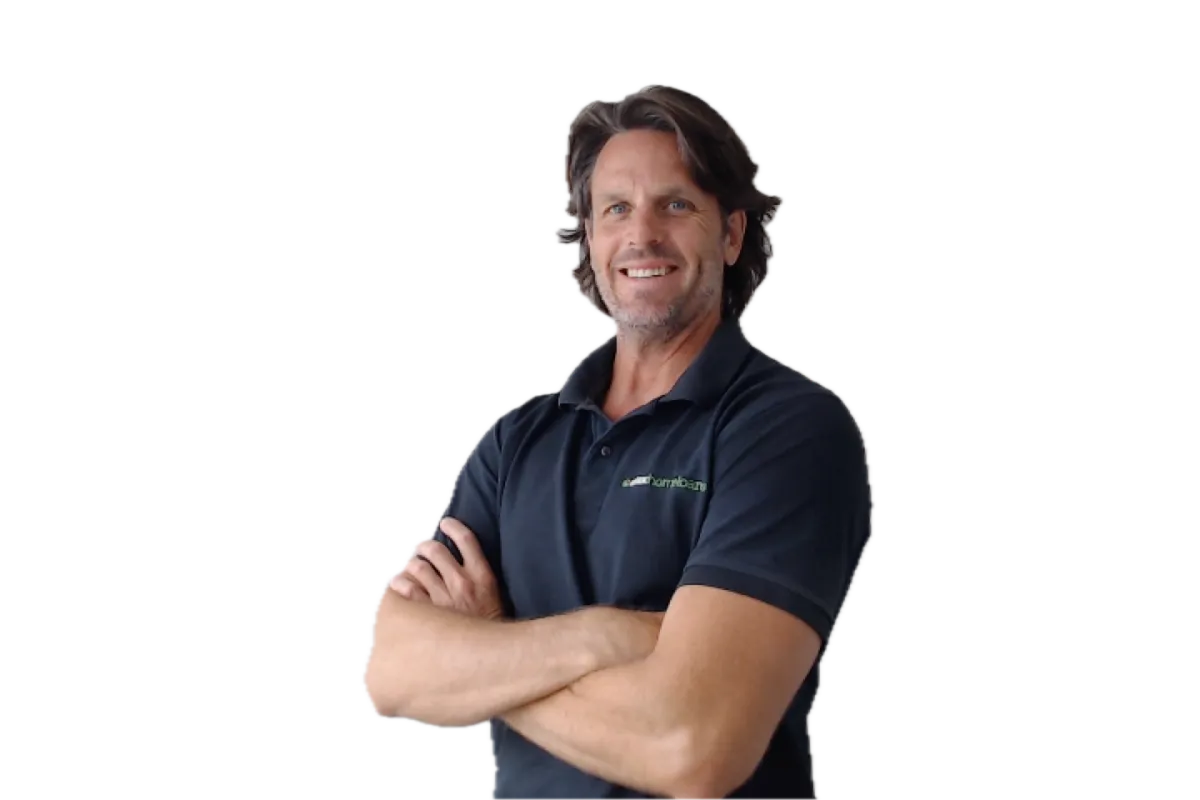
MEET THE DIRECTOR & BROKER
Hey, I'm Ollie !
Why Work With Me?
Jargon-Free Guidance
A proven track record 15+ Years
150+ 5 Star Google Reviews
R2BG Finance Pty Ltd ACN 146 520 596 Australian Credit Licence 389898. AFCA Membership No. 35040. Privacy Policy